
Talking finances with your aging parents: tips for helpful conversations


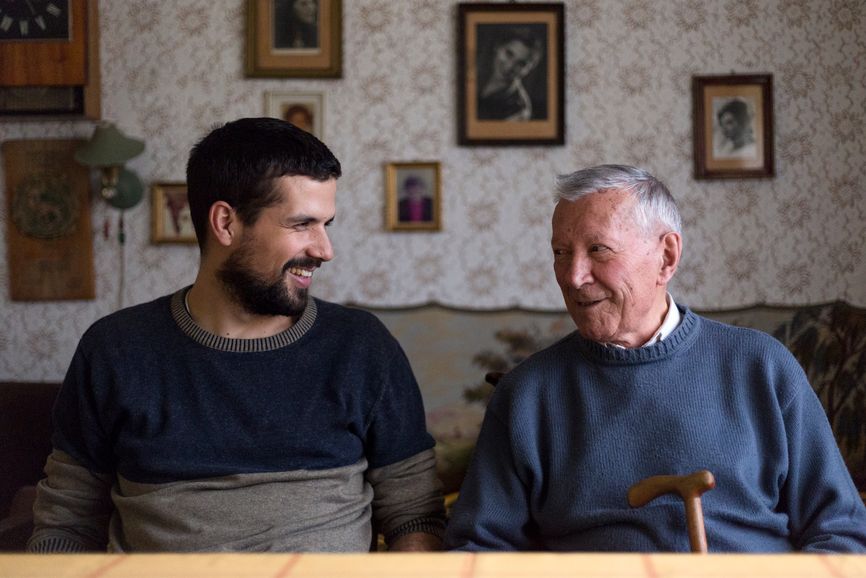
Discussing finances with your aging parents is an essential step to ensure their financial security and well-being. By approaching the conversation with empathy, patience, and a clear plan, you can support your parents both financially and emotionally. Keeping an open line of communication can help prevent financial mismanagement, strengthen family bonds, and ensure a secure future for your parents.
From opening your first savings account to helping pay for your college tuition, your parents managed most, if not all, of your finances as you were growing up. As your parents age, that responsibility can shift, and there may be a time when you must talk to them about their finances.
But having an open discussion about anyone’s finances, let alone your parents, can feel challenging and awkward. However, an open conversation about finances can be crucial for ensuring your parents’ financial security and well-being as they age.
“I would encourage people to have the conversation. It’s key and it’s important,” Beth Ludden, a senior vice president in CareScout’s long-term care insurance business, says. “Being in crisis mode is not the time to make a sound decision about finances.”
By keeping lines of communication open, approaching sensitive topics like health, aging, and money with empathy and care, you can help your parents navigate their financial future with confidence and peace of mind.
Signs your aging parent may need help with their finances
You know your parent well. Be conscious of repeated or out-of-character financial behavior. These are some of the signs that they may be losing track of their money:
Expensive new purchases they can’t afford: Did your parent recently buy a boat or vehicle that you’re concerned they can’t safely operate or afford? Has their lifelong thriftiness suddenly given way to frequent purchases from TV shopping channels? Out-of-character purchases, excessive lottery ticket spending, or signs of a scam may mean it’s time to take a more active role in their accounts.
Piles of unopened mail: Look at the envelopes to see whether any are marked “Final notice” or contain other warnings. You shouldn’t open your parent’s mail without permission, but reviewing the unopened envelopes with them can help you understand the scope of the problem.
Regular calls asking for money: Calls from collectors, nonprofits requesting donations, or acquaintances asking for money could indicate that your parent’s finances are less secure than you realized. If new “friends” have entered the picture, or unwelcome old ones have returned, try to learn whether your parent is giving away more money than they can afford or has fallen victim to a scam.
Difficulty with simple, everyday math: If calculating a tip or dividing stitches on knitting needles suddenly becomes difficult, gently ask whether other basic calculations have become harder, too.
Taking longer to complete routine financial tasks: Notice whether online bill pay has become difficult or checks are bouncing. Has your parent filed tax returns on time and kept the related records organized?
Increased gambling: As with excessive lottery ticket spending, frequent trips to a casino or more time spent on gambling games may be a reason to check in. Ask how much your parent is spending and whether gambling is affecting the money available for regular expenses.
Becoming forgetful about cash: Many families have stories about finding cash tucked into dresser drawers, pockets, under mattresses, or even inside walls. If your parent can’t keep track of the cash on hand, the issue can grow beyond having to search for it while packing up the home.
Complaining about never having enough money: If your parent frequently says there isn’t enough money, ask whether you can review the checkbook or bank account together, or accompany them to the bank.
Even if you’re not concerned about your parent’s mental or physical health, it’s important to become familiar with their finances as they age. The sooner you begin talking openly about money and learning how they currently manage it, the more comfortable they may feel including you in major decisions, such as selling their home, choosing assisted living, or making new investments.
How to approach your aging parents about their finances
Whether they’re calling you by your nickname or making sure you get enough to eat during a holiday dinner, your parents are your parents, and it’s always been their job to take care of you — even if you have a career, a home, or a family of your own. As your parents age and need assistance with finances it can be difficult for you, and them, to accept new roles and a shift in the family dynamics.
Make sure to start the conversation off slowly. Even if you’re coming from a place of love and support, requesting access to bank accounts and other personal information can be off-putting. Start off with an open discussion on finances.
The earlier you begin the conversation, the easier it is to step in when your parents need assistance. Helping your parents manage their money or just talking to them about their finances isn’t just about a doomsday scenario either. It can be for a practical reason like they’re traveling out of the country and want you to have access to their checking account.
Whatever the reason, here is a list of ways to broach the subject of finances with your aging parents:
Consider their needs
With a topic as personal as finances, it can be hard to know how to start the conversation. It depends on the relationship you have with your parents, but it’s always best to approach a financial discussion with respect and support while considering your parents’ needs first.
Ask yourself, why now?
There are plenty of reasons why you might want to discuss your parents’ financial situation and they might be a good segue into starting a conversation about finances. Whether they’re traveling out of the country, or they had a sudden health scare, think about an event that might open the door for an open discussion. Always come from a place of compassion and let your parents know you want what’s best for them.
Educate your parents on common scams that target older adults
Many scammers specifically target older adults through fake tech support, identity theft, and extortion. In 2023, total financial losses by people over the age of 60 topped $3.4 billion, an almost 11 percent increase from 2023, according to the Federal Bureau of Investigation’s 2023 Elder Fraud Report. Discussing common scams can go a long way in preventing one from happening as well as opening the door to a broader discussion on finances.
Include loved ones
Including other family members can add another perspective to the situation and make your parents feel more comfortable. But before you start sending out invites, talk with your parents about who they would like to include.
Consider long-term care costs
As if the topic of finances wasn’t sensitive enough, discussing long-term care costs can be equally sensitive. It’s hard to imagine a point where you don’t have total independence and how much that might cost. Planning for long-term care can be a great way to talk about funds and other resources available to your parents.
Revisit the conversation
As you head into a talk with your parents about their finances, be prepared to revisit the conversation.
“Go in with the attitude that the first time you broach the topic you may get shut down,” Ludden says. “It can be a sensitive discussion and people really value independence, especially with their children.”
Encourage your parents to voice any concerns or changes in their preferences over time. Let them know that they don’t have to decide everything right now, and they can always revisit the conversation when they’re ready.
The benefits of discussing finances with aging parents
Even if your parents are retired accountants or investment bankers, it can still be beneficial to go over finances with them as they age. Here are a few of the benefits of discussing finances with your aging parents:
Ensuring financial security
Understanding your parents' financial situation allows you to help them budget, manage their debt, and plan for future expenses.
Planning for future needs
Your parents’ financial needs may change as they age, especially in terms of healthcare and aging care. Discussing finances ensures they are prepared for these costs, and they can choose the type of care they want
Reduce family conflicts
Open financial discussions can prevent misunderstandings and conflicts among family members. A clear, documented estate plan or other advanced directives makes sure everyone is on the same page and that your parents’ wishes are respected.
Strengthen your relationship
Talking about finances with your parents can bring you closer to your parents. It shows you care about their well-being and are willing to support them. These discussions can build trust and communication.
7 financial questions to ask when managing your aging parents’ finances
Once your parents agree to go over their finances, you can guide the conversation with these seven questions:
1. What are your current sources of income?
Understanding where your parents’ money is coming from — whether it’s from pensions, Social Security, annuities, investments, or a part-time job — will help give you a clear picture of their financial health.
2. Do you have a budget for monthly expenses?
Ask your parents about their day-to-day expenses such as bills, groceries, and medications. Knowing what their budget is can help identify where they might need assistance with adjustments.
3. Do you have any debts or outstanding loans?
It’s important to know if your parents have any debts like a mortgage, credit card balances, or personal loans. Debt can be hard for some people to talk about, especially if it’s a large amount of money, so be sensitive to what your parents might be feeling about their debt.
4. Have you planned for long-term care?
Discuss their plans for potential long-term care needs. Ask your parents if they have long-term care insurance or other benefits in place to cover the cost of in-home care or other aging care options.
5. Do you have an estate plan, will, or trust?
An estate plan outlines your parents’ wishes for their assets and property. Ask if they have a will, trust, or other legal documents in place. If they don’t you can suggest they meet with an estate planning attorney. You may also want to talk to your parents about power of attorney and who they would want to make decisions for them.
6. Who is your financial advisor?
Knowing who your parents trust with their financial matters is important. This could be a financial advisor, attorney, or accountant. Knowing who this is lets you contact them if needed.
7. Do you have copies of your financial information?
If your parents enlist your help in managing their finances it’s essential for you to have information on bank accounts, insurance policies, investment accounts so you can manage their finances effectively and respect their wishes. This should include passwords and contact information.
How to stay organized when helping manage finances
If you do eventually take responsibility for your parent’s finances, it can require time, persistence, and patience. You may need to locate records, contact several institutions, and learn how your parent has handled routine expenses. Following these steps may make the process easier and help you stay organized.
Find and organize important financial documents: Start by gathering important personal papers and financial records. Store them in a secure place where the appropriate people can find them when needed. These records should include:
Social Security cards
Marriage certificates
Birth certificates
Home titles
Mortgage information
Vehicle titles
Investment statements
Health insurance policies
Property insurance policies
Retirement account statements
Medical and doctor records
Safe-deposit box information
Bank account numbers
Review cash flow: With your parent’s involvement or the appropriate legal authority, review financial accounts, bank statements, and the checkbook register. Make a complete list of income, including pensions, government assistance, and disability benefits. Then list expenses, including utilities, mortgage and vehicle payments, credit card bills, and other monthly costs. Comparing income and expenses can help you see how much money comes in, where it goes, and which obligations require regular attention.
Organize estate planning documents: Find out whether your parent has a living will, living trust, last will, revocable trust, or other estate planning documents. Keep in mind that estate planning documents should be updated every five to seven years. Use this opportunity to understand your parent’s healthcare wishes and formalize them with the appropriate paperwork. Make sure you know where the originals and copies are stored and who should have access to them. If these documents aren’t in place, work with your parent and a qualified lawyer to create, update, or otherwise review them.
Document everything you do: Whether you’re paying bills by check or buying personal items for your parent with cash, keep a record of every transaction completed on their behalf. Save copies of checks and detailed receipts, and take thorough notes when meeting with attorneys or other professionals. Organize the records so you can find them when questions arise. These details are essential for showing your siblings that you’re managing your parent’s affairs responsibly and can help everyone stay informed.
Consider working with a financial planning team: Tax preparers, estate planning or elder law attorneys, and financial planners or advisors can help you avoid costly mistakes while managing your parent’s affairs. They can help you decide how to budget your parent’s money, organize responsibilities, and address financial questions that are outside your experience. Their involvement may also reassure your siblings that you’re not handling every financial decision alone.
Look for low-income assistance: Not every older adult has substantial assets or savings. If your parent is facing financial difficulty, consider consulting government resources. These organizations can help you navigate complex benefit systems, understand available support, and identify local assistance:
Area Agencies on Aging
Administration on Aging
Veterans Affairs
The best time to talk with your parent about finances is while they’re still self-sufficient and able to make informed decisions. This allows them to remain in control of the plan and explain how you should help manage their money and long-term care if support becomes necessary. Planning ahead also gives you time to gather documents, clarify responsibilities, and involve siblings before an urgent problem develops. By working together and seeking help from qualified professionals when needed, you can protect your parent’s wishes, finances, and sense of control as they age.
Their finances, your support
The goal of talking to your aging parents about their finances is to create a supportive environment. As you talk with your parents, volunteer to do some of the financial research for them or check if your job has any financial counseling benefits.
Whether you’re helping them plan for long-term care, preparing for an estate plan, or just trying to help them organize their budget, your involvement can help your parents make informed decisions. A proactive approach, handled with empathy and understanding, can make a positive impact on your parents' lives as they age.
Want more information on long-term care costs?
Long-term care is an important cost to consider when you’re talking to your parents about their finances. Use our guide to understand long-term care costs and how to pay for them.
Expert reviewed by


Beth Ludden
Beth Ludden is a Senior Vice President in CareScout’s long-term care insurance business. She has 30+ years working in insurance with a focus on long term-care planning solutions and public policy issues related to older population care needs.
Written by
Brian Dowd
Brian is writer based in New England. He is a passionate storyteller with a knack for finding the extraordinary in the ordinary. He joined CareScout as a Senior Content Writer in 2024. Before that, he worked as a content writer in the senior living industry and worked for several years as an assi...